

Green Dot - Mobile Banking
by Green Dot
3.5
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 3.5
- Price
- Free
- Download
- 5.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
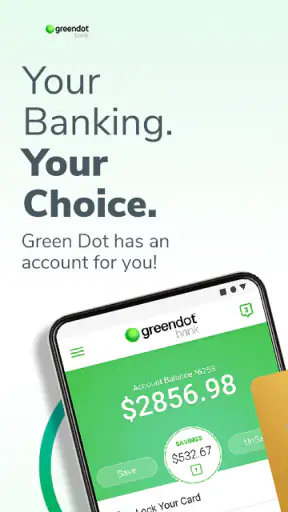
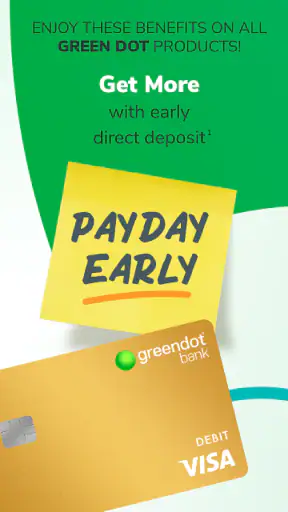
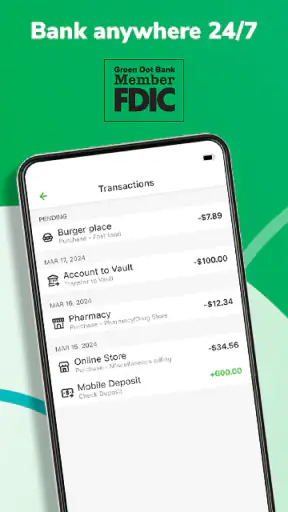
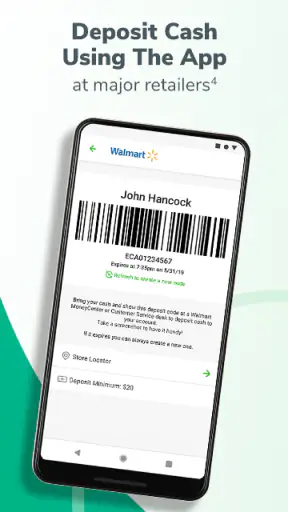
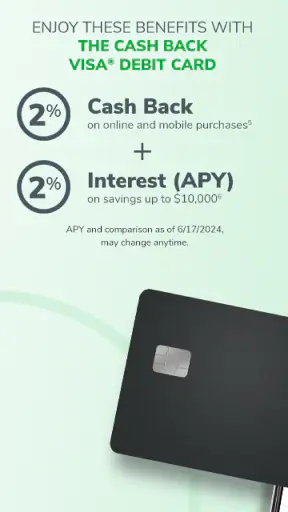
 Analysis by Getfullapps
I tend to judge a banking app by what happens between the obvious moments: when I am standing in a checkout line, moving through a weak-signal area, or trying to check a transaction before deciding whether I can afford something. Green Dot - Mobile Banking is built for that kind of quick access. It is a free finance app from Green Dot, and its simple promise is less about making banking exciting than putting everyday account tasks on a phone.
After spending time with it, I see the appeal clearly. The app is aimed at people who want their banking close at hand rather than tied to a desktop browser or a branch visit. At the same time, a mobile banking experience is only as convenient as the connection around it. That matters here: checking a balance, reviewing activity, or handling an account task can become frustrating if the app cannot communicate reliably with its service. Green Dot works best when I treat it as a connected banking tool, not as a substitute for an offline wallet or a permanent record of account information.
How Green Dot feels in everyday mobile banking
The first thing I notice about this app is its practical focus. It belongs in the finance category, is rated for Everyone, and is available at no cost. Green Dot is the developer, and the app has been available since May 17, 2011, which gives it a long history compared with many newer mobile finance tools. Its current version is 4.69.5, and it can run on devices using Android 7.0 or later.
That broad device support is useful if I am keeping an older phone for banking instead of upgrading frequently. It also makes the app easier to consider for family members who do not use the newest hardware. Still, compatibility alone does not guarantee a smooth session. An older phone may have less storage, slower performance, or a less dependable connection, so I would keep the operating system updated when possible and avoid judging the service only from a single rushed attempt.
The audience is fairly easy to identify. I would recommend it to someone who wants a straightforward way to stay close to a Green Dot account while away from a computer. It can be especially handy for checking whether a recent purchase has appeared, looking at available funds before paying, or keeping an eye on activity during a busy day. Someone who prefers doing all financial tasks in a desktop browser may find a phone-centered approach less comfortable, but for mobile-first users, the format makes sense.
The app has an average rating of 3.5 from around 91 thousand ratings, with roughly 33 thousand written reviews. I read that as a mixed but meaningful signal rather than an automatic rejection. Banking apps are judged during stressful moments, and a problem with login, loading, or transaction visibility feels more serious than a minor issue in a casual app. The rating suggests that the experience will not be equally smooth for everyone, so I would install it with realistic expectations and test the important parts before relying on it heavily.
What changes when the connection is weak
Connectivity is not a background detail in mobile banking. When I open Green Dot to confirm a balance or inspect an unfamiliar charge, I am expecting current account information. That normally requires the app to reach its service. In a strong connection, the process feels appropriately direct; in a poor one, loading can take longer or a session may not complete in the way I expect.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
This is why I would not make an important spending decision from a screen that has been sitting open for a while. A displayed balance can become outdated after another purchase, deposit, or account change. If I am at a checkout counter, I prefer to refresh shortly before paying rather than trusting an earlier view. That habit is useful with any connected banking app, but it matters particularly when the phone has moved between Wi-Fi and cellular service.
There is also a practical difference between having a signal and having a dependable connection. A phone can show network coverage while the service is slow, congested, or interrupted. If Green Dot is taking time to load, I would avoid repeatedly tapping buttons, especially around a payment or account action. Repeated attempts can create uncertainty about whether the first request went through. Waiting for a clear result is less stressful than guessing.
I would also avoid opening the app for the first time in a place where I already know the connection is unreliable. Setting up access, responding to a sign-in request, or checking recent activity is better done before leaving home. That gives me a chance to notice any account issue while I still have time to solve it, instead of discovering the problem beside a payment terminal.
Useful mobile situations, and the ones that are less comfortable
The strongest use case is quick awareness. Suppose I am buying groceries after work and want to make sure a previous transaction did not reduce my available funds more than expected. A short mobile check can help me make a more informed decision without finding a computer. The value is not that the phone replaces financial planning; it is that the account is within reach when a real-life decision arrives unexpectedly.
Another useful situation is travel within a familiar routine. I might check activity after using the account in several places, or review a transaction while I still remember where and when it happened. Looking soon after a purchase makes the details easier to recognize. If I wait until the end of the week, several similar entries can be harder to distinguish.
There is a trade-off, though. A phone is convenient but visually limited compared with a desktop screen. If I need to study a long sequence of transactions, compare several dates, or make a careful budget, I would rather use a larger display or a dedicated budgeting method. Green Dot is better for staying connected to the account than for replacing a full financial workspace.
I also would not use a public, borrowed, or unfamiliar device for sensitive account access simply because my own phone is inconvenient. The mobile format encourages quick actions, but speed should not remove basic caution. I prefer to use my own device, check the surrounding screen before entering information, and close the session when I am finished in a shared environment.
The app’s Everyone age rating makes it broadly approachable, but that does not mean every user should manage an account without guidance. A younger or inexperienced user may still need help understanding available funds, pending activity, and the difference between seeing a transaction and resolving a problem. The interface can make access easier; it cannot replace financial judgment.
When something fails: a calmer recovery routine
My biggest advice is to separate a connection problem from an account problem. If the app does not load, I first check whether the phone has a stable connection and whether other services are responding. I then try again once, rather than repeatedly submitting the same action. If the issue continues, I would wait for a better connection before assuming that the account itself is affected.
This matters during a purchase. If a screen appears frozen after I initiate something, I would not immediately repeat the action. I would look for a clear confirmation, check the account activity later, and keep any relevant receipt. The goal is to avoid turning one uncertain attempt into several. A receipt, time, and merchant name can also make a later support conversation much easier.
For sign-in trouble, I would work through the account recovery route carefully and avoid guessing credentials over and over. Too many failed attempts can make an already stressful situation harder. I would also distinguish between forgetting access details and losing connectivity; the solutions are different, and treating them as the same problem wastes time.
One limitation of a mobile banking app is that it can make urgent support feel less convenient when the app itself is the place I normally go for help. If the connection is poor, I may need to move somewhere with a more dependable signal before I can investigate. That is not a reason to avoid Green Dot, but it is a reason to keep basic account records and transaction receipts available outside the app.
I would create a small personal recovery habit: check important activity when the connection is strong, save receipts for unusual purchases, and avoid making repeated attempts when a request has an unclear status. Those steps are more valuable than simply reinstalling the app at the first sign of trouble. Reinstallation can remove local friction, but it does not solve a service interruption or an account issue.
Using it without wasting mobile data
Green Dot is not the kind of app I would leave open continuously just to watch an account. Banking information is most useful when I have a specific reason to check it. Opening the app for planned moments—before a larger purchase, after an unfamiliar transaction, or during a regular money review—keeps the experience focused and avoids unnecessary network use.
When I am on limited cellular data, I prefer to use a trusted Wi-Fi connection for longer account reviews and reserve mobile data for a quick check. I would not connect to an unknown public network merely to save a small amount of cellular data, because protecting account access is more important than reducing a brief network session.
A useful compromise is to prepare before going out. I can review recent activity at home, note the amount I expect to have available, and then use the app on the move only when something has changed. This does not turn the app into an offline banking tool, and I would not assume that a previously viewed screen remains current. It simply reduces unnecessary opening and refreshing.
I also avoid refreshing while the phone is switching between networks. If I have just left a building or a Wi-Fi hotspot, I wait until the cellular connection is stable before attempting a sensitive account action. That small pause prevents a lot of ambiguous loading screens. It is a particularly useful habit for commuters, shoppers, and anyone who moves through areas with uneven coverage.
Notifications and background behavior are worth considering as part of a broader phone routine, but I would make choices based on my own data plan and privacy comfort. I do not need a banking app competing for attention every minute. A deliberate check is often better than reacting to every alert without context, especially when I am trying to understand a group of transactions rather than one isolated event.
How it compares with familiar alternatives
Compared with visiting a branch, Green Dot is more convenient for quick account awareness and does not require planning a trip around opening hours. Compared with a desktop banking site, it is easier to use while away from home but less comfortable for extended reviews. Compared with a budgeting app, it is closer to the account itself and therefore more useful for checking actual activity, while a budgeting tool may be better for organizing spending across categories or accounts.
That distinction helps me decide where it belongs. I would use Green Dot as the immediate account window, not as my only financial system. A spreadsheet, notebook, or budgeting application can provide a wider view of spending; the banking app can help verify what has actually happened. Using both for different jobs is more sensible than expecting one small screen to handle every financial task.
People who need sophisticated planning, detailed reporting, or a broad view across multiple financial providers may prefer a more comprehensive finance platform. People who mainly want mobile access to their Green Dot account may find those alternatives unnecessarily complicated. The right choice depends less on the number of features and more on whether the app matches the way I actually manage money.
Green Dot is also not ideal for someone who regularly works in locations with unreliable connectivity and needs dependable access at the exact moment of a purchase. In that situation, I would plan ahead, keep a separate payment backup, and avoid assuming that the app can answer an urgent question without a working connection. That is a general mobile-banking trade-off, but it is important enough to shape the decision.
Who I would recommend it to
I would recommend Green Dot to a mobile-first user who wants a free way to stay close to a Green Dot account and is comfortable doing routine checks from a phone. The app makes the most sense for quick balance awareness, transaction review, and account access during ordinary daily movement. Its long availability and more than five million installs show that it has reached a substantial audience, although popularity should not replace personal testing.
I would be more cautious recommending it as the sole tool for someone who needs detailed financial organization, depends on weak-signal environments, or expects every banking task to feel as comfortable as it does on a desktop. I would also encourage a new user to test access at home, review how the app behaves on their particular phone, and understand their own backup plan before relying on it during travel or an important purchase.
The free price removes one obvious barrier to trying it, and the Everyone rating makes it accessible to a wide audience. Those are practical advantages, but they do not eliminate the need for secure phone habits or careful transaction checking. I like the app most when I use it deliberately: open it for a reason, confirm that the information is current, and give unclear requests time to resolve instead of tapping through uncertainty.
My connectivity verdict
Green Dot - Mobile Banking is a useful everyday finance app when I have a reliable connection and want account access without reaching for a computer. Its strongest quality is convenience in real situations: before paying, after a purchase, or while checking activity during a busy day. The experience is less convincing when I expect the phone to work as an offline reference or as a complete replacement for broader financial planning.
My final view is positive but practical. I would install it for mobile access to a Green Dot account, keep my important receipts, and avoid making urgent decisions from an outdated screen. If your routine includes dependable connectivity and quick account checks, this free app is worth considering. If your priority is deep budgeting, large-screen organization, or guaranteed access in poor-signal places, I would pair it with another method rather than asking it to do everything.
Pros
- Simple mobile banking tools for everyday money management
- Early direct deposit may provide access to paychecks sooner
- Cash deposits are available at participating retail locations
- Customizable transaction alerts help monitor account activity
- No minimum balance requirement makes the account easy to maintain
Cons
- Some features and benefits require qualifying direct deposits
- Cash deposit locations may charge fees or have availability limits
- Out-of-network ATM withdrawals can result in additional charges
- Customer support quality may vary depending on the issue
- Mobile banking access depends on a reliable internet connection
FAQs for Green Dot - Mobile Banking
What is Green Dot Mobile Banking, and who can use it?
Green Dot Mobile Banking is a financial app designed for managing eligible Green Dot accounts from an Android or iOS device. After signing in, users can typically review balances, monitor transactions, deposit eligible checks, transfer money, and manage certain card settings. Availability depends on the account type, location, identity verification, and Green Dot’s current eligibility requirements, so the app is mainly intended for existing or newly approved Green Dot customers.
Is Green Dot Mobile Banking safe to use for everyday banking?
The app includes standard security features such as account login protection, identity verification, transaction monitoring, and options to control or lock a supported card. However, no banking service is completely risk-free. Download the application only from an official app store, use a strong and unique password, enable available security options, and avoid signing in over unsecured public Wi-Fi. Green Dot may also require additional verification for sensitive actions.
What banking features are available in the Green Dot app?
The available tools can vary by Green Dot product, but the app generally lets customers check account balances, view transaction history, receive account notifications, manage a linked debit card, and locate options for adding or moving money. Some users may also have access to mobile check deposit, direct deposit information, bill payment, or transfers. Before downloading, review the features connected to your specific Green Dot account.
Are there fees for using Green Dot Mobile Banking?
Downloading the Green Dot Mobile Banking app is generally separate from the fees that may apply to your account or card. Depending on the product and activity, charges can potentially include monthly service fees, out-of-network ATM fees, cash reload fees, expedited services, or other transaction-related costs. Fee rules may change and differ between Green Dot products, so read the applicable account agreement and fee schedule before using the service.
Can I deposit checks, add cash, or transfer money with Green Dot Mobile Banking?
Many Green Dot customers can add money through supported methods, but the exact options depend on their account, eligibility, limits, and location. The app may support direct deposit, mobile check deposit, bank transfers, or cash deposits through participating retail locations. Processing times, deposit limits, verification requirements, and possible fees can apply. Always confirm the method and terms shown inside the app before completing a transaction.

Green Dot - Mobile Banking
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via customeronlinefeedback@greendot.com, visit http://greendot.com, or review their https://m2.greendot.com/app/help/legal/techprivacy.










